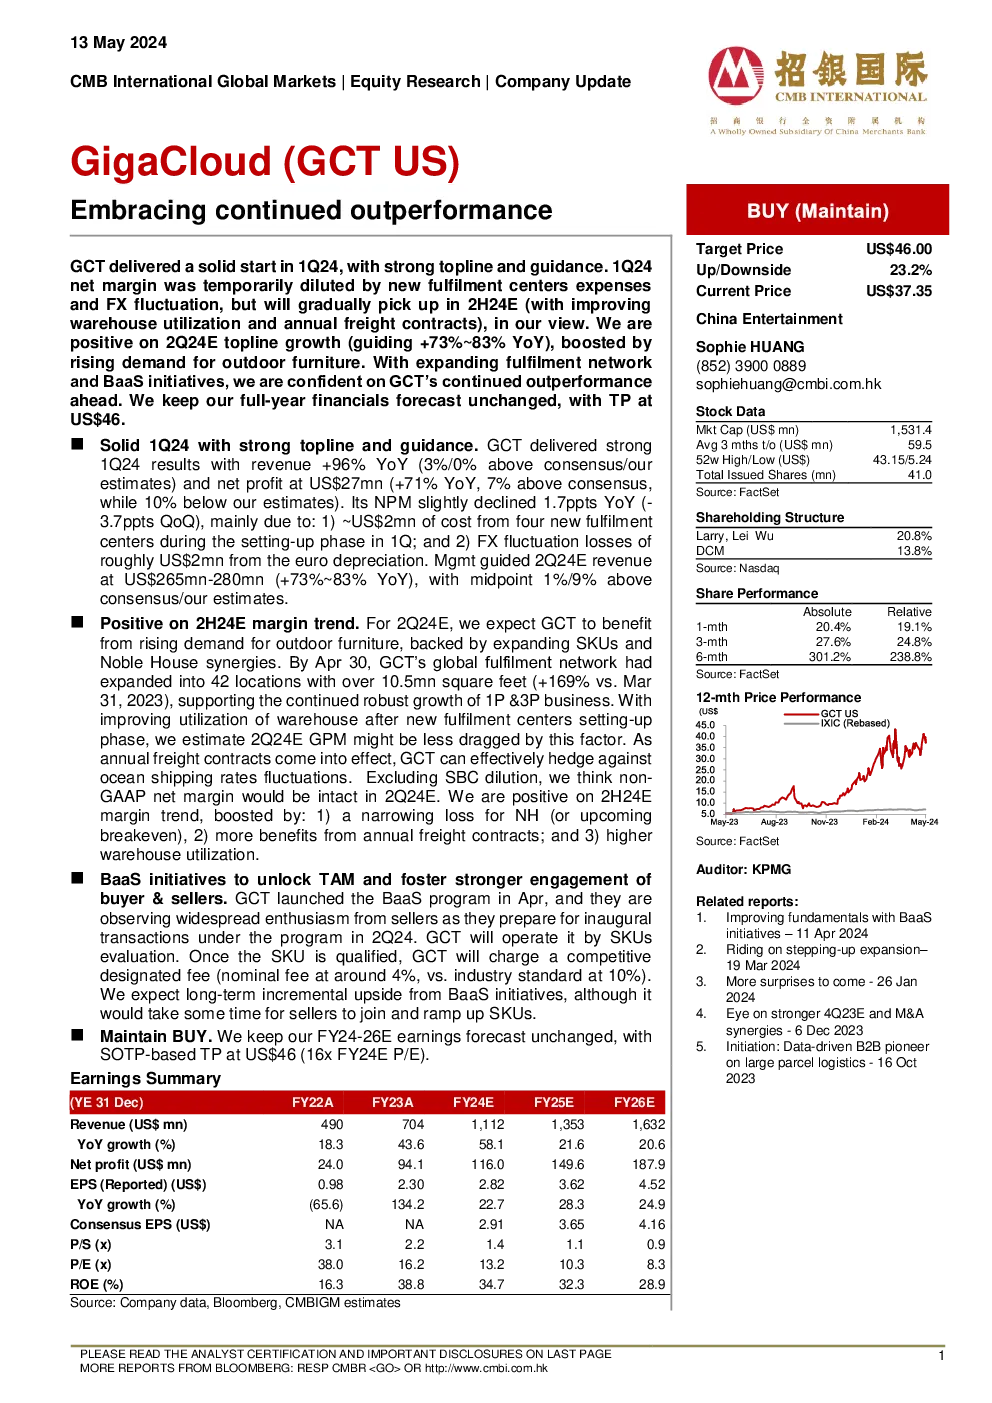
GigaCloud (GCT US) is performing exceptionally well, as evidenced by its strong start in the first quarter of fiscal year 2024. The company reported impressive revenue growth of 96% year-over-year, slightly exceeding expectations. Net income was reported at USD 27 million, with a net profit margin of 21.2%, albeit seeing a slight decline compared to the previous quarter due to new fulfillment center expenses and foreign currency fluctuations.
For the second quarter of fiscal year 2024, GCT expects continued revenue growth, projecting an increase of between 73% to 83% compared to the same period last year. This growth is driven by increased demand for outdoor furniture and the expansion of its fulfillment network.
GCT's performance in the second half of fiscal year 2024 is anticipated to be positive, with benefits from the growing demand for outdoor furniture, improved supply chain efficiencies due to annual freight contracts, and higher warehouse utilization rates. The introduction of the BaaS (Battery-as-a-Service) plan is expected to unlock additional market opportunities and foster closer engagement between buyers and sellers.
Maintaining the same financial forecast, analysts predict a target price of USD 46 per share, reflecting a potential upside of approximately 23%. The stock currently trades at USD 37.35, indicating significant room for growth based on analyst projections.
GigaCloud's BaaS initiative aims to improve the company's fundamental performance by offering competitive fees to sellers while leveraging SKU evaluations. This strategy is anticipated to bring incremental growth over time.
Despite facing challenges such as increased competition, economic uncertainty, and geopolitical tensions, GigaCloud continues to demonstrate resilience and growth potential, backed by its robust financial performance and strategic initiatives.