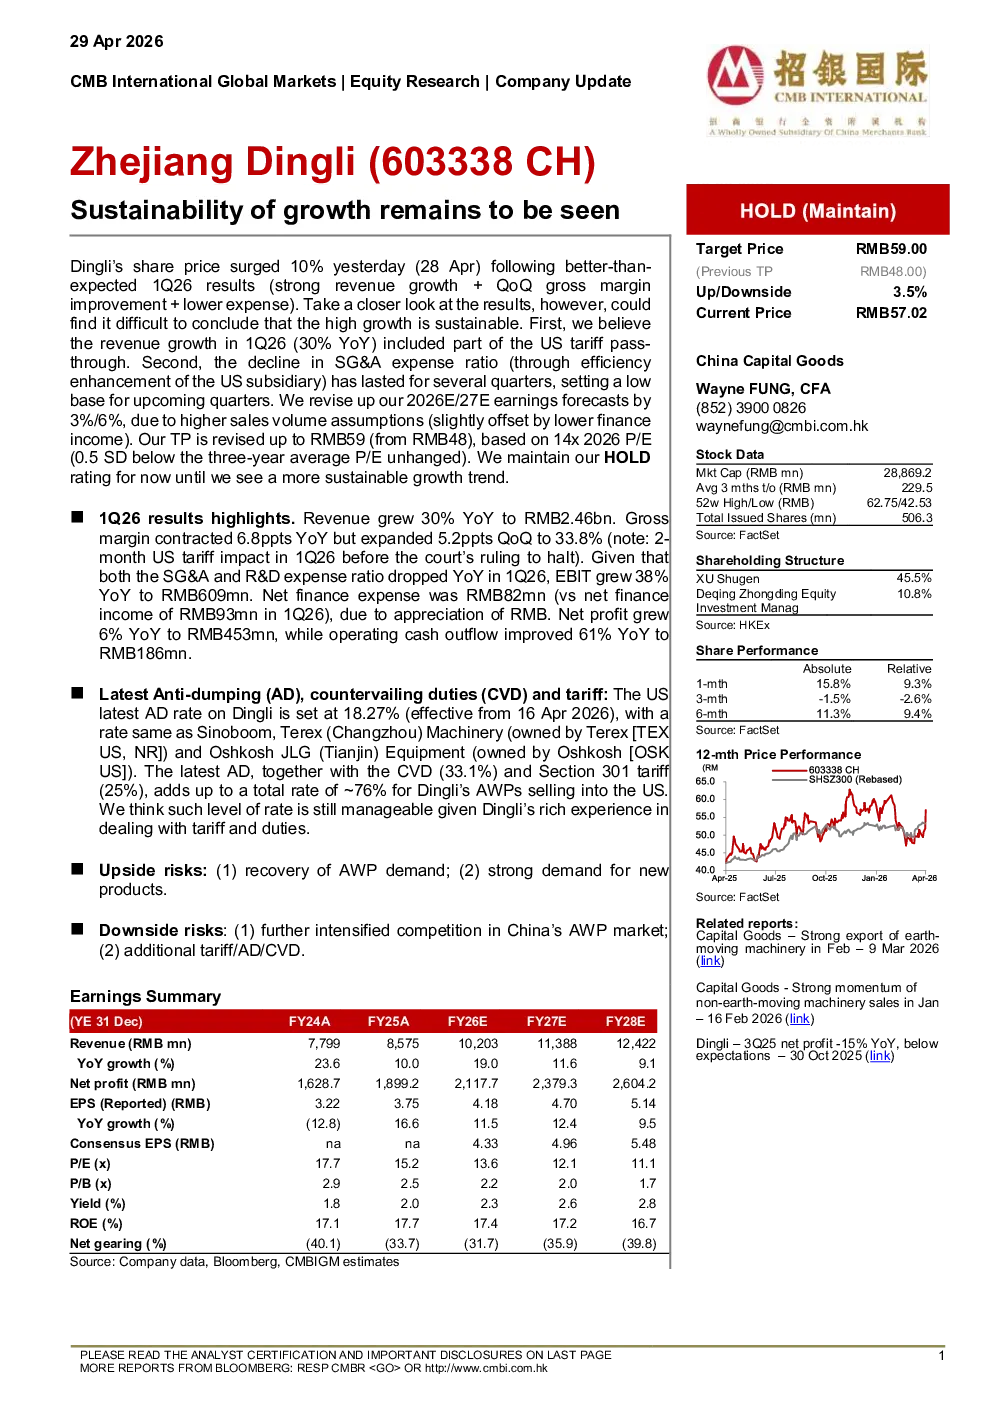
Dingli shares surge 10% on 1Q26 results, but sustainability of growth remains uncertain.
1Q26 highlights:
- Revenue grew 30% YoY to RMB2.46bn, partly driven by US tariff pass-through.
- Gross margin contracted 6.8ppts YoY but expanded 5.2ppts QoQ to 33.8% (2-month US tariff impact included).
- SG&A and R&D expense ratios dropped YoY, boosting EBIT by 38% YoY to RMB609mn.
- Net profit grew, though net finance expense was RMB82mn due to RMB appreciation.
Challenges:
- Revenue growth may include tariff pass-through effects.
- SG&A expense ratio decline has been sustained, setting a low base for future quarters.
Latest trade duties:
- US AD rate on Dingli is 18.27%, combined with CVD (33.1%) and Section 301 tariff (25%), total rate ~76% for US AWP sales.
Risks:
- Upside: AWP demand recovery, strong new product demand.
- Downside: Intensified competition in China's AWP market.
Forecasts revised up for 2026/27 earnings.
Current target price is RMB59.00, with a BUY rating.