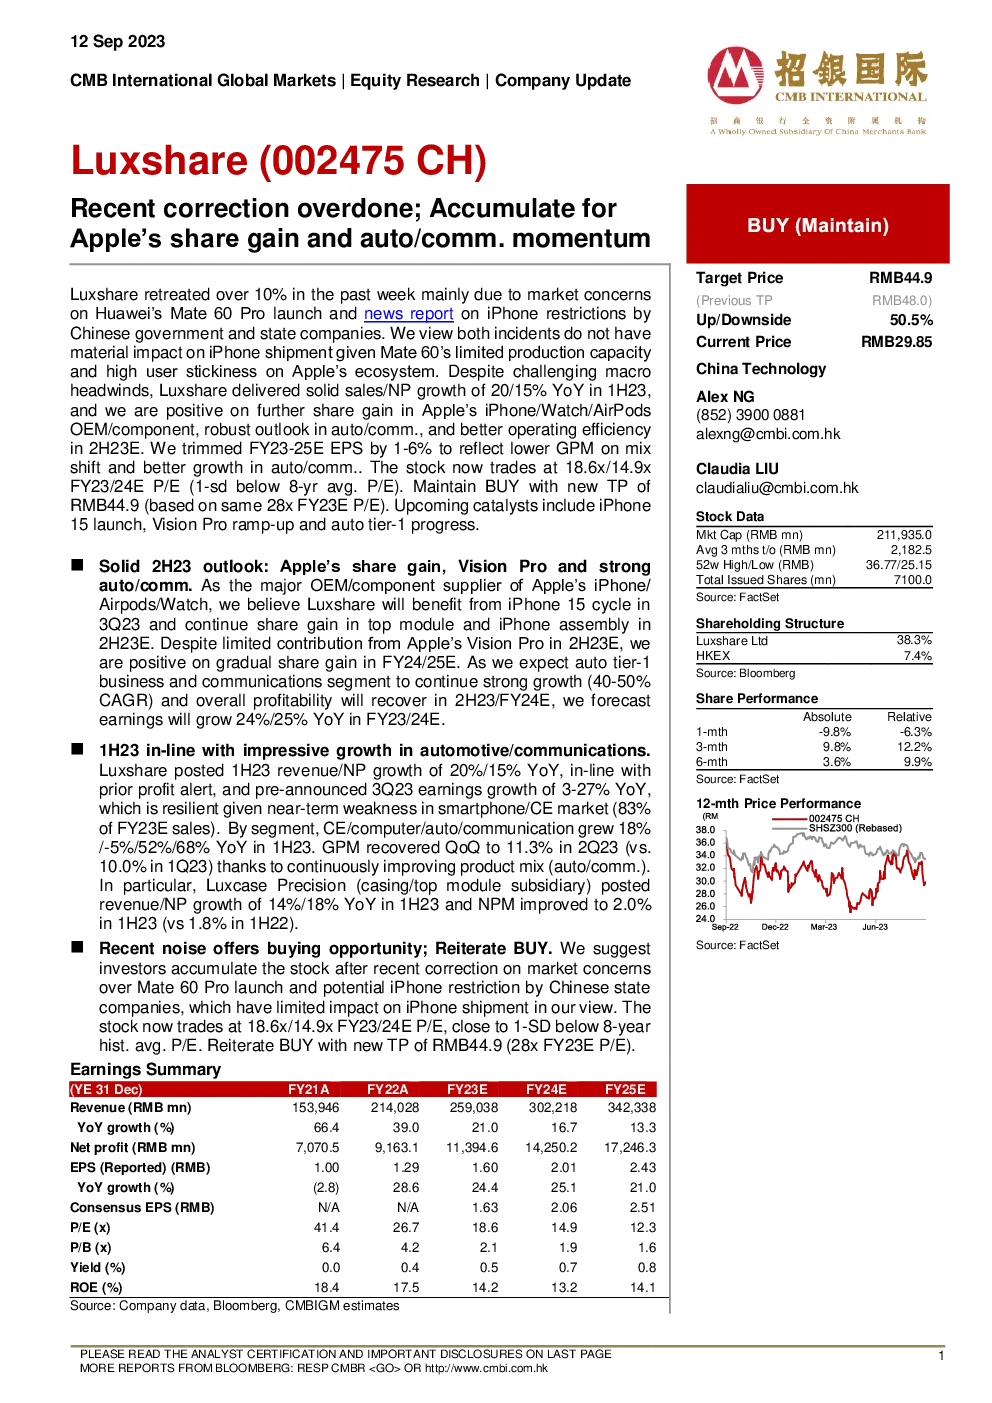
Luxshare, a leading provider of components and original equipment manufacturing (OEM) services to Apple and other companies, has seen its stock price drop over 10% in the past week due to market concerns over the release of Huawei's Mate 60 Pro and potential restrictions on iPhones by the Chinese government and state-owned enterprises. However, the report suggests that these events have limited impact as Mate 60's production capacity is constrained and iPhones' user stickiness is high within Apple's ecosystem.
Despite challenging macroeconomic headwinds, Luxshare reported strong sales and net profit growth of 20% and 15% respectively for the first half of 2023. The company is expected to benefit from further increases in its share of Apple's iPhone, Watch, and AirPods OEM/assembly activities, as well as in its automotive and communication sectors.
The report acknowledges that there will be a reduction in full-year earnings estimates for FY23 and FY25 due to lower gross profit margins from automotive and communication business transitions, but expects a return to profitability in the second half of 2023 and fiscal years 2024 and 2025 with a projected 24% and 25% year-over-year growth in profits.
Luxshare is currently trading at a price-to-earnings ratio of 18.6 times and 14.9 times for FY23 and FY24, respectively, which is close to the historical average of one standard deviation below the eight-year mean P/E ratio. Despite this, the stock is recommended for a 'Buy' rating with a new target price of 44.9 yuan based on a 28 times FY23 P/E ratio.
Key catalysts include the release of iPhone 15, upgrades to Apple's Vision Pro, and progress in the auto Tier-1 segment. The report notes that the stock offers an attractive buying opportunity following recent market corrections related to Mate 60 Pro and potential Chinese government restrictions on iPhones.
Luxshare's performance in the first half of 2023 was particularly impressive given the softness in the smartphone and consumer electronics markets, with resilience evident across segments such as consumer electronics/computers, automotive, and communications. The company's gross margin improved in the second quarter of 2023, reaching 11.3%, thanks to a better product mix, especially in the automotive and communication sectors.
The report also highlights that the stock is attractively valued compared to peers, offering a significant discount to the average P/E ratio for comparable companies. The recommendation is to accumulate shares in light of recent market corrections, as the company is expected to benefit from continued growth in iPhone sales, Vision Pro contributions, and robust performance in the automotive and communication sectors.
发现报告(www.fxbaogao.com)是金融圈都在用的专业研报平台,用户量特别大。我们致力于提供最全的研报数据,不管是宏观经济还是具体公司的财报,这里应有尽有,报告多到您看不完。凭借先进的技术和简洁的页面,我们帮您省去了大量筛选的时间,让获取关键信息变得轻而易举,绝对是您投资路上的好帮手。