Northam Platinum Holdings 2026Q4财报及Vision2031战略会议纪
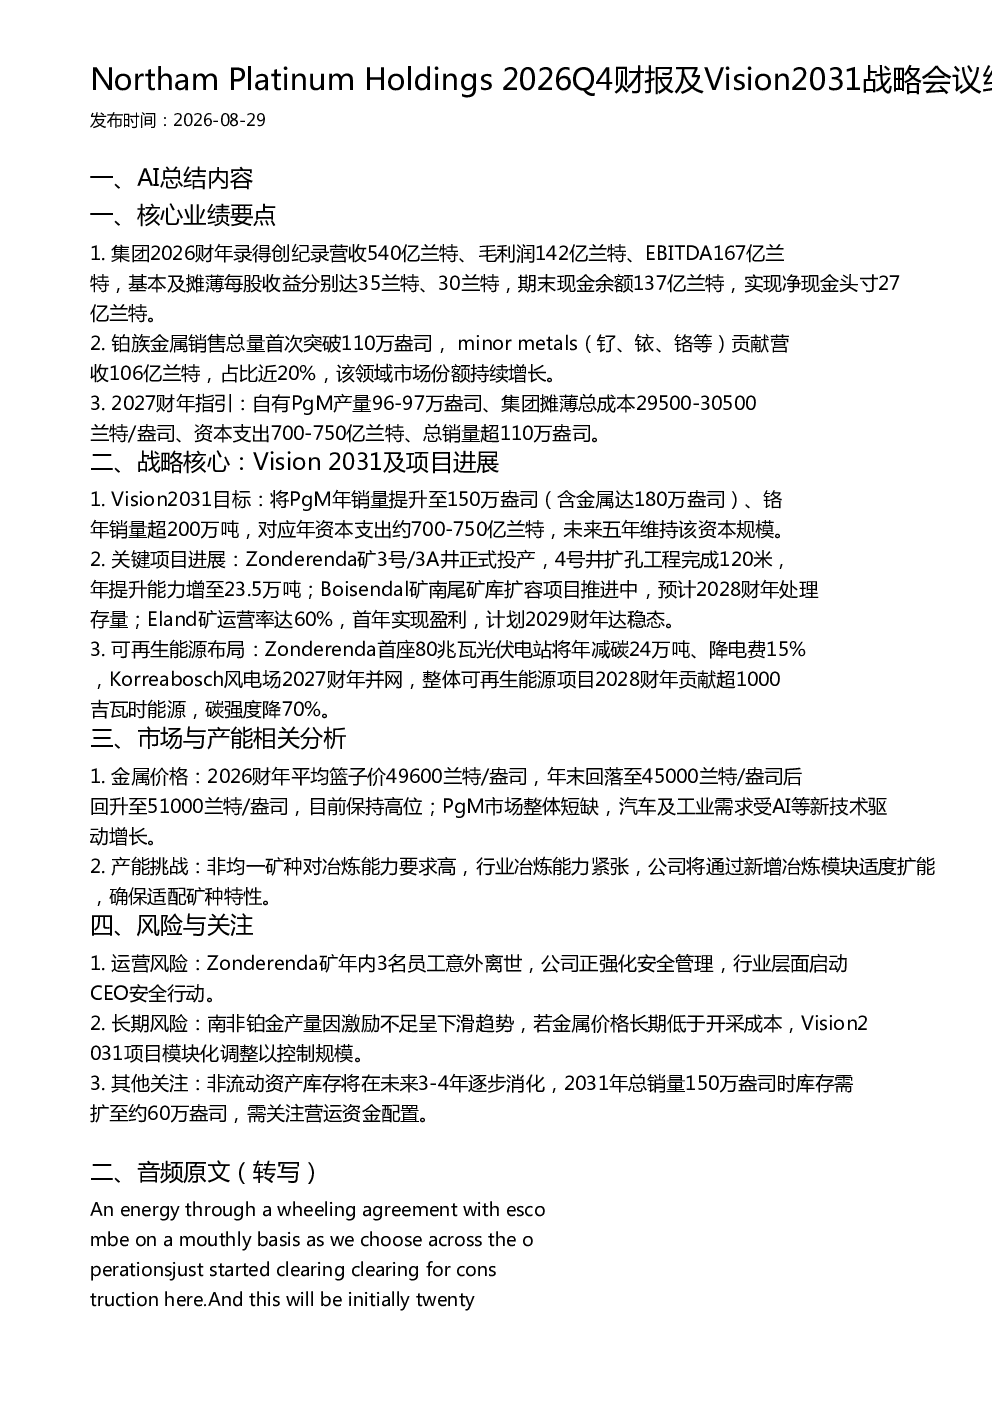
发布时间:2026-08-29 一、AI总结内容 一、核心业绩要点 1. 集团2026财年录得创纪录营收540亿兰特、毛利润142亿兰特、EBITDA167亿兰特,基本及摊薄每股收益分别达35兰特、30兰特,期末现金余额137亿兰特,实现净现金头寸27亿兰特。 2. 铂族金属销售总量首次突破110万盎司, minor metals(钌、铱、铬等)贡献营收106亿兰特,占比近20%,该领域市场份额持续增长。 3. 2027财年指引:自有PgM产量96-97万盎司、集团摊薄总成本29500-30500兰特/盎司、资本支出700-750亿兰特、总销量超110万盎司。 二、战略核心:Vision 2031及项目进展 1. Vision2031目标:将PgM年销量提升至150万盎司(含金属达180万盎司)、铬年销量超200万吨,对应年资本支出约700-750亿兰特,未来五年维持该资本规模。 2. 关键项目进展:Zonderenda矿3号/3A井正式投产,4号井扩孔工程完成120米,年提升能力增至23.5万吨;Boisendal矿南尾矿库扩容项目推进中,预计2028财年处理存量;Eland矿运营率达60%,首年实现盈利,计划2029财年达稳态。 3. 可再生能源布局:Zonderenda首座80兆瓦光伏电站将年减碳24万吨、降电费15%,Korreabosch风电场2027财年并网,整体可再生能源项目2028财年贡献超1000吉瓦时能源,碳强度降70%。 三、市场与产能相关分析 1. 金属价格:2026财年平均篮子价49600兰特/盎司,年末回落至45000兰特/盎司后回升至51000兰特/盎司,目前保持高位;PgM市场整体短缺,汽车及工业需求受AI等新技术驱动增长。 2. 产能挑战:非均一矿种对冶炼能力要求高,行业冶炼能力紧张,公司将通过新增冶炼模块适度扩能,确保适配矿种特性。 四、风险与关注 1. 运营风险:Zonderenda矿年内3名员工意外离世,公司正强化安全管理,行业层面启动CEO安全行动。 2. 长期风险:南非铂金产量因激励不足呈下滑趋势,若金属价格长期低于开采成本,Vision2031项目模块化调整以控制规模。 3. 其他关注:非流动资产库存将在未来3-4年逐步消化,2031年总销量150万盎司时库存需扩至约60万盎司,需关注营运资金配置。 二、音频原文(转写) An energy through a wheeling agreement with escombe on a mouthly basis as we choose across the operationsjust started clearing clearing for construction here.And this will be initially twenty megawatts growing to forty megawatts producing initially fifty five megawatt hours of energy anddisplacing sixty thousand tons of carbon by anim.At eland we have a truly unique opportunitytrape the firstpg. M mine in south africa operatingsolely on renewable energy.In addition eland iswater positive and we will phase out external water sources before the end of the decade trulybecoming a green minei'll now hand you over to alead to take us through the financials thank you.Thank you paul good morning everybodythis is the expanded footprint of the boys and all sortstailing stand we are tripling the size of the dam to provide a full life of mine solution and work is progressing wellthe expanded dam will be operational in around ten months time and this will enable increased throughput at the south concentrator and thereby the increase in mining production required for vision twenty thirty one.Tocontextualize the regulatory challenges of projects in this country permitting for the stand took more than three years and capects will amountto almost one billion rant.Looking at the key financial features for the year under review.Thishas been yet another record year for northern the uptic and natal prices applied to our record sales volumes resulted in record revenue of fiftyfour billion landsthis allowed us to post a gross profits of fourteen point two billion rand and a record eberdar of sixteen point seven billion rand and this whilst continuing to invest in organic growth ensuring our long term sustainabilityprimary responsibility of any serious miningcompanywe also delivered record basic earnings perchet and a record headline earnings perchet ofthirty five rand and thirty rand respectivelyinaddition we closed the year in a neat cash position.Looking now at bravenuerevenue improved bysixty four per cent to fifty four billion roundsthis increase is primarily driven by a fifty seven point four per cent improvement in the round four e basket price together with an eight per cent increase in sale volumeswalf prices softenedsomewhat during the second half they have sincerebounded and remained well above recent historical levels.And p j market signalling remains positive.Accordingly we are forging ahead with vision twenty thirty one.This will not only expandour business to one and a half million ounces but will also provide bullet proofing against potential future market shocksthe focus of our mining growth is u g two and this provides an outsized benefit from the not so minor metals rutheniumiridium and chromethese combined contributed almost twenty per cent all ten point six bullion ran to our revenue this past year and our share of these markets.Continues to grow looking now atcost of sailssales revenue increased by sixty four per centwhilst cost of sales increased by thirty six per cent.This led to a gross profit offourteen point two billion rand.At a gross profit margin of twenty six point two per cent.Reflecting the improved pricing and production volumesmovements in the individual elements making up costs of cells include a six and a half per centincrease and square meats his mind together withan average wage increase of approximately six and a half per cent late to mining costs increasing by eleven when one per centconcentrating costs increased by eleven point six per cent due toadditional costs incurred on various recovery enhancement projectssmalter and bass natal removalplan costincrease by fourteen point seven per cent due to increase tongue smolted.Royalty charges increased in line with revenue and the profitability of the group.Schebay's payment expensesincreased in line with the northern shape priceand the group's increased profitability led to an increase in the contributions to the toro employe empowerment trust