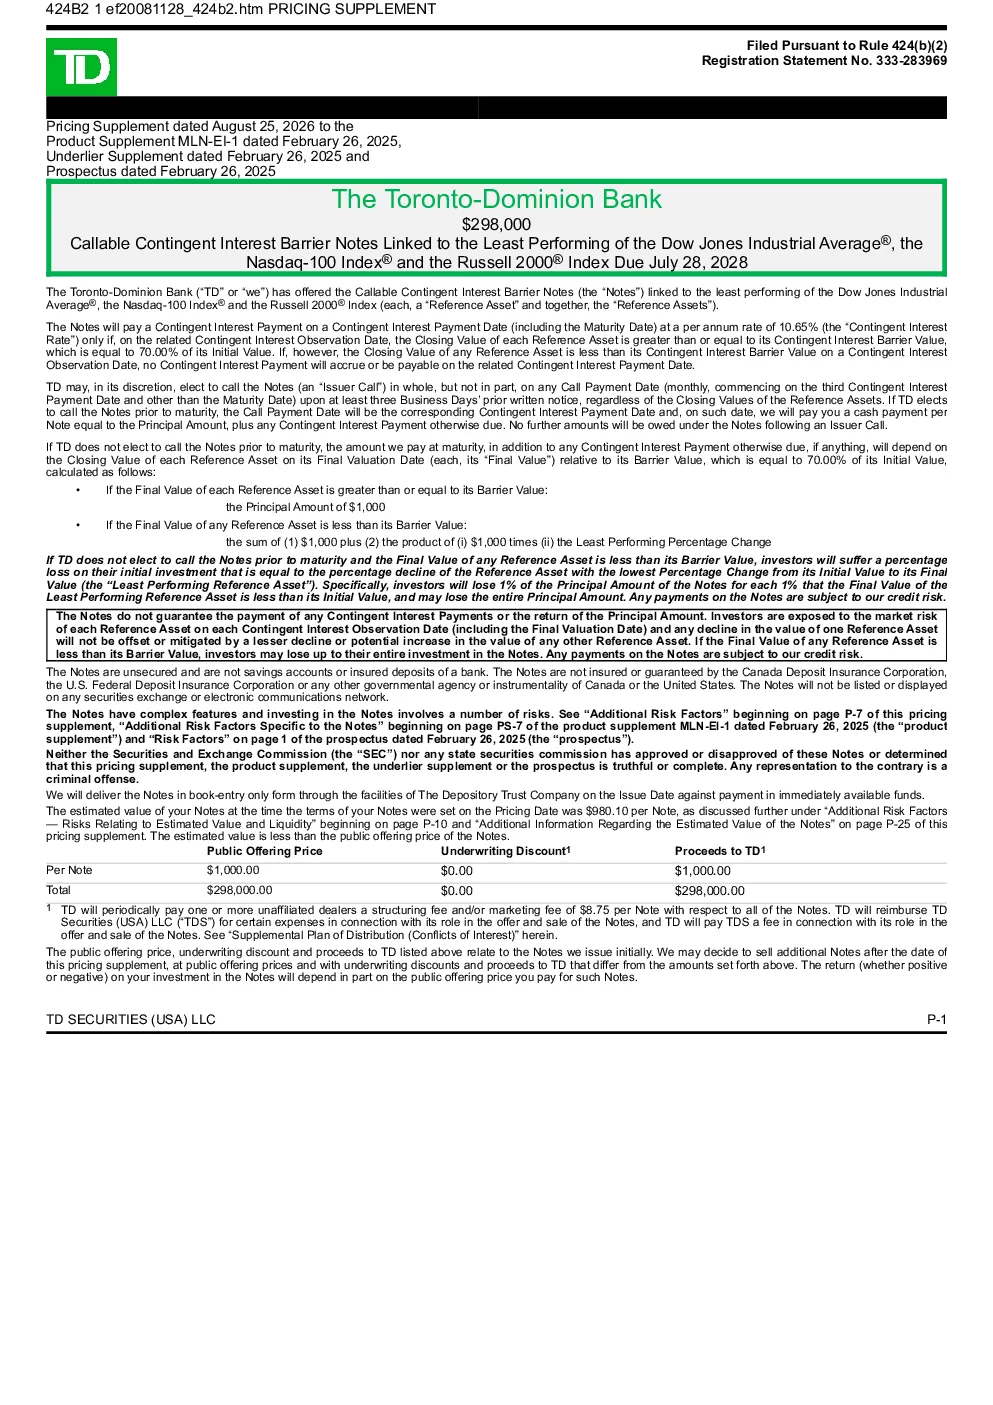
The Toronto-Dominion Bank (TD) has offered Callable Contingent Interest Barrier Notes linked to the least performing of the Dow Jones Industrial Average®, the Nasdaq-100 Index®, and the Russell 2000® Index, with a maturity date of July 28, 2028. The Notes pay a Contingent Interest Rate of 10.65% per annum if the closing value of each Reference Asset is greater than or equal to its Contingent Interest Barrier Value (70.00% of its Initial Value) on the related Contingent Interest Observation Date. If the closing value of any Reference Asset is less than its Contingent Interest Barrier Value, no Contingent Interest Payment will be paid.
TD may call the Notes in whole on any Call Payment Date (monthly, commencing on the third Contingent Interest Payment Date) with at least three Business Days’ prior notice, regardless of the Reference Assets’ values. If called before maturity, the payment will be the Principal Amount plus any accrued Contingent Interest Payment. If not called, the payment at maturity will depend on the Final Value of each Reference Asset relative to its Barrier Value: $1,000 plus the product of $1,000 and the Least Performing Percentage Change if the Final Value is greater than or equal to the Barrier Value; otherwise, it will be the Principal Amount plus the product of $1,000 and the Least Performing Percentage Change.
Key risks include:
- Return Risk: The Notes do not guarantee principal repayment or Contingent Interest Payments. Investors may lose up to their entire investment if the Final Value of any Reference Asset is below its Barrier Value.
- Issuer Call Risk: TD may call the Notes early, limiting the holding period and reinvestment risk.
- Market Risk: Investors are exposed to the market risk of each Reference Asset on each Contingent Interest Observation Date, with no diversification benefit.
- Liquidity Risk: The Notes are unlisted and may lack an active secondary market, potentially leading to significant losses if sold before maturity.
- Tax Risk: The U.S. tax treatment is uncertain, with potential implications for ordinary income treatment, capital gains, and Medicare taxes.
- Credit Risk: Payments are subject to TD’s credit risk, and changes in credit ratings may negatively impact market value.
The estimated value of the Notes at the Pricing Date was $980.10 per Note, lower than the public offering price, reflecting costs, expected profits, and hedging activities. The estimated value is based on TD’s internal funding rate and models, which may differ from other institutions’ methodologies.