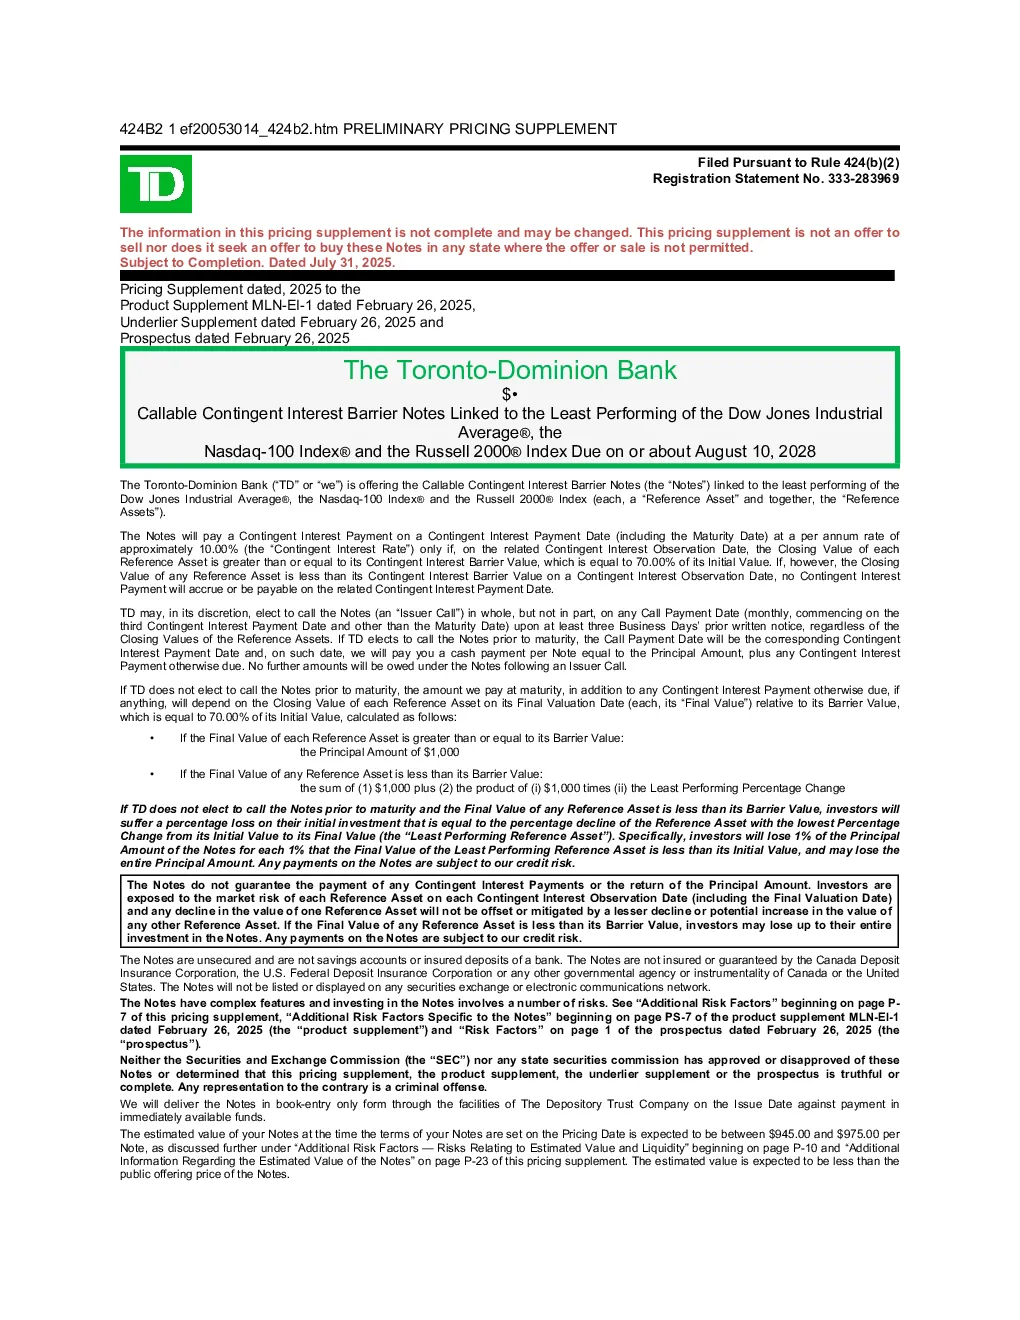
The Toronto-Dominion Bank (TD) is offering Callable Contingent Interest Barrier Notes linked to the least performing of the Dow Jones Industrial Average® (INDU), the Nasdaq-100 Index® (NDX) and the Russell 2000® Index (RTY). The Notes will pay a Contingent Interest Payment at a rate of approximately 10.00% per annum only if the Closing Value of each Reference Asset is greater than or equal to its Contingent Interest Barrier Value (70.00% of its Initial Value). If the Closing Value of any Reference Asset is less than its Contingent Interest Barrier Value on a Contingent Interest Observation Date, no Contingent Interest Payment will accrue or be payable on the related Contingent Interest Payment Date.
Key Features:
- Term: Approximately 3 years, subject to an Issuer Call.
- Reference Assets: Dow Jones Industrial Average® (INDU), Nasdaq-100 Index® (NDX), Russell 2000® Index (RTY).
- Contingent Interest Rate: Approximately 10.00% per annum.
- Contingent Interest Barrier Value: 70.00% of the Initial Value of each Reference Asset.
- Issuer Call Feature: TD may elect to call the Notes in whole on any Call Payment Date (monthly, commencing on the third Contingent Interest Payment Date) upon at least three Business Days’ prior written notice, regardless of the Closing Values of the Reference Assets.
- Payment at Maturity:
- If the Final Value of each Reference Asset is greater than or equal to its Barrier Value: Principal Amount of $1,000.
- If the Final Value of any Reference Asset is less than its Barrier Value: $1,000 + ($1,000 × Least Performing Percentage Change).
Risks:
- Return Risk: The Notes do not guarantee the return of the Principal Amount and investors may lose up to their entire investment if the Final Value of any Reference Asset is less than its Barrier Value.
- Contingent Interest Payment Risk: Investors will not receive the Contingent Interest Payment if the Closing Value of any Reference Asset is less than its Contingent Interest Barrier Value on the relevant Contingent Interest Observation Date.
- Liquidity Risk: The Notes are not listed and there may be little or no secondary market for the Notes, potentially resulting in significant losses if the Notes need to be sold before maturity.
- Credit Risk: Investors are subject to TD’s credit risk, and any decrease in TD’s credit ratings or increase in the credit spreads charged by the market for taking TD’s credit risk is likely to adversely affect the market value of the Notes.
- Taxation Risk: The U.S. tax treatment of the Notes is uncertain and could differ materially from the treatment described in the pricing supplement.
Estimated Value: The estimated value of the Notes at the time the terms of the Notes are set on the Pricing Date is expected to be between $945.00 and $975.00 per Note, as discussed further under “Additional Risk Factors — Risks Relating to Estimated Value and Liquidity”.
Examples:
- Example 1: TD elects to call the Notes on the First Potential Call Payment Date, resulting in a total return of 1.6666%.
- Example 2: The Closing Value of at least one Reference Asset is less than its Contingent Interest Barrier Value on each Contingent Interest Observation Date prior to the Final Valuation Date, TD does NOT elect to call the Notes Prior to Maturity, and the Final Value of Each Reference Asset Is Greater Than or Equal to Its Barrier Value and Contingent Interest Barrier Value, resulting in a total return of 0.8333%.
- Example 3: The Closing Value of at least one Reference Asset Is Less Than Its Contingent Interest Barrier Value on Each Contingent Interest Observation Date Prior to the Final Valuation Date, TD Does NOT Elect to Call the Notes Prior to Maturity, and the Final Value of at Least One Reference Asset Is Less Than Its Contingent Interest Barrier Value and Barrier Value, resulting in a loss of 60.00%.
Conclusion:
Investors should be aware of the risks associated with the Notes, including the potential for loss of principal, limited liquidity, and uncertain tax treatment. The Notes are linked to the performance of the least performing of the three Reference Assets, which increases the risk of no Contingent Interest Payments and a significant loss of principal at maturity. Investors should carefully consider their investment objectives and risk tolerance before investing in the Notes.