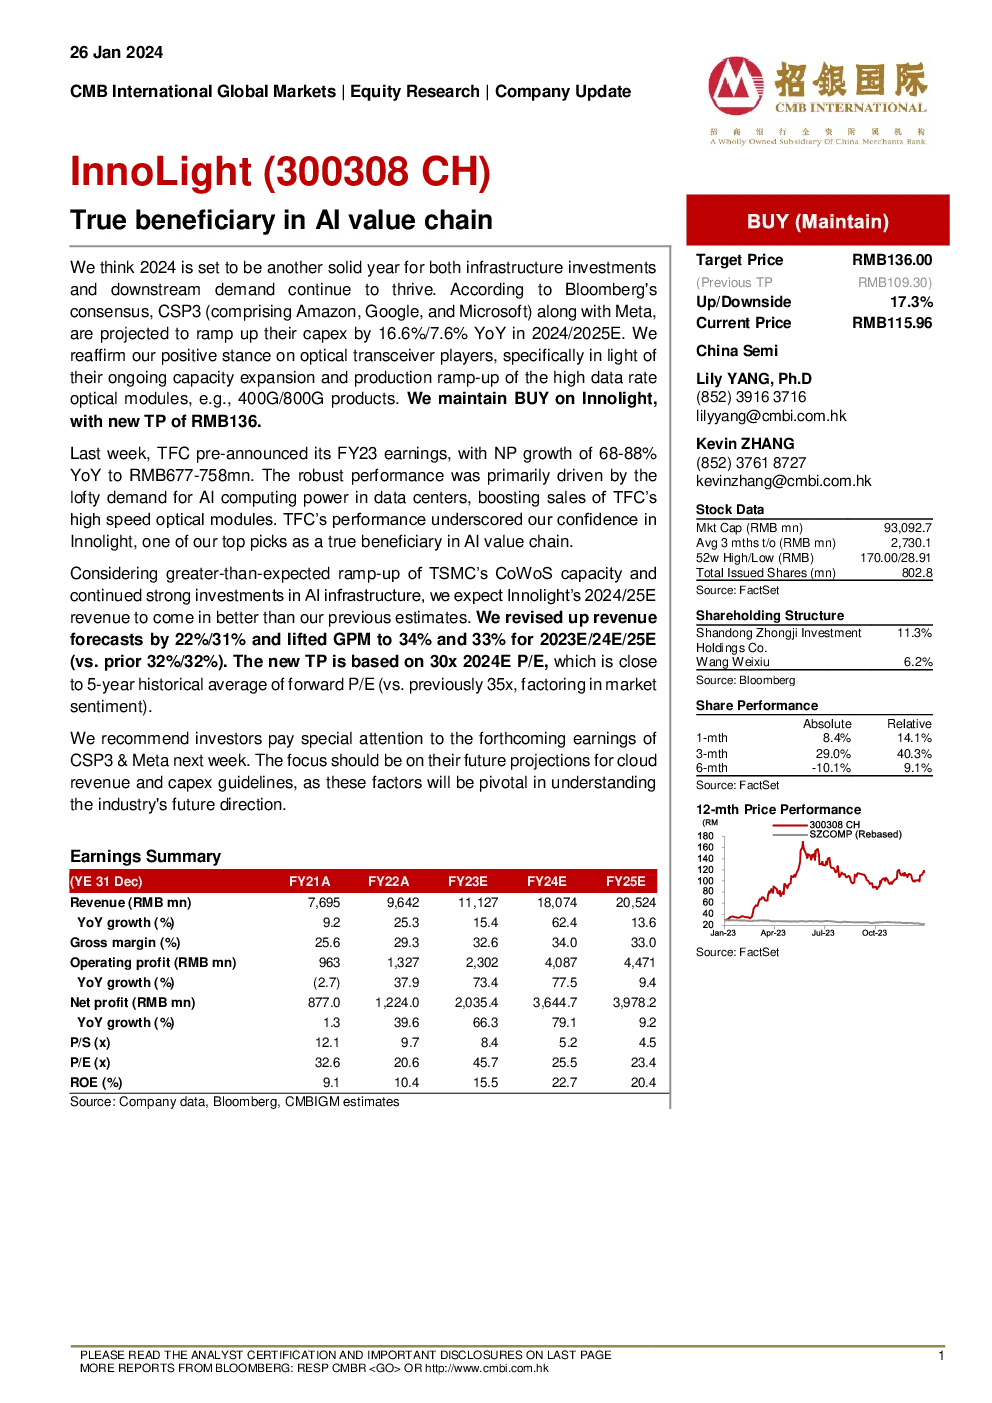
InnoLight Technologies, a company focusing on optical transceivers and high-speed optical modules, has been identified as a significant beneficiary in the AI value chain. The stock's target price has been set at 136 yuan, representing a 17.3% increase from its previous target of 109.30 yuan. As of the current market price of 115.96 yuan, this suggests an attractive potential for investors.
For the fiscal year ending December 31, 2023, InnoLight reported a net profit growth of 68-88%, reaching between 6.77 and 7.58 billion yuan. This strong performance is attributed to the robust demand for AI computing power from data centers, which significantly boosted sales of high-speed optical modules.
With the forecasted growth in TSMC's CoWoS capacity exceeding expectations and continued strong investment in AI infrastructure, it is anticipated that InnoLight will outperform earlier predictions for fiscal years 2024 and 2025. Revenue estimates have been revised upwards by 22% and 31% respectively, and Gross Profit Margin (GPM) projections have been adjusted to 34% and 33% for the fiscal years 2024 and 2025, compared to previous forecasts of 32%.
The new target price of 136 yuan is based on a 30 times multiple of the 2024 earnings per share (EPS), aligning closely with the historical average five-year forward P/E ratio. This adjustment reflects a more conservative valuation approach considering market sentiment.
In light of the strong performance indicators and the strategic positioning within the AI ecosystem, investors are encouraged to pay close attention to upcoming earnings reports from key players like Amazon, Google, Microsoft, and Meta, particularly focusing on their cloud revenue and capital expenditure guidance. These insights are crucial for gauging the industry's future trajectory.